Flagler Beach Real Estate Risks: What Could Slow Appreciation
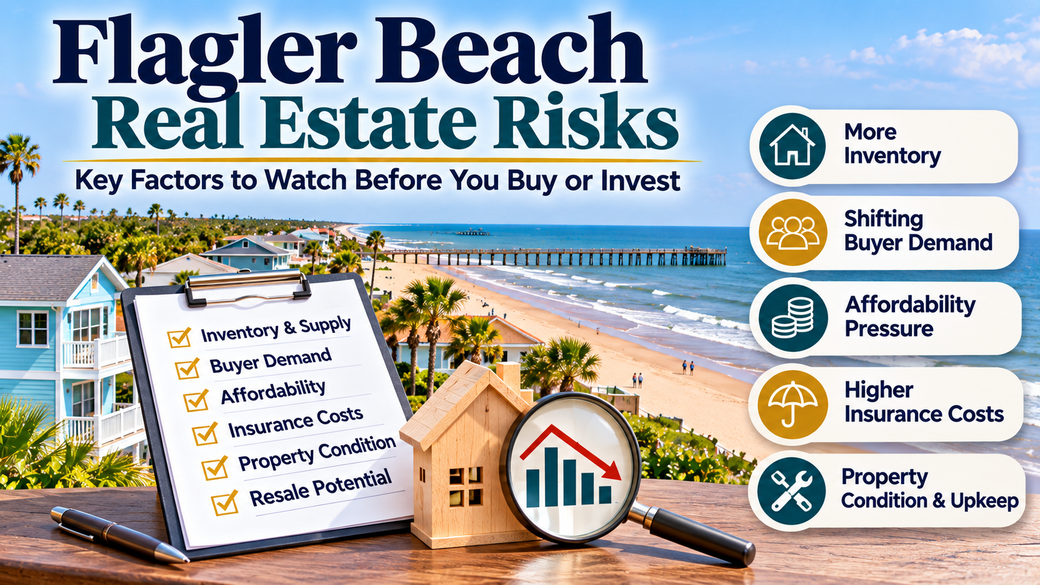
Flagler Beach real estate risks are most likely to slow appreciation through higher ownership costs, softer buyer urgency, and a larger selection of comparable homes. For relocation buyers, the key is to test the full carrying cost before making an offer, not just the list price. Coastal appeal can support long-term demand, but insurance, financing, property condition, and inventory can narrow the resale buyer pool. This guide identifies the variables worth watching before committing capital in Flagler Beach.
Who Should Read This
This guide is for buyers weighing long-term value, investors stress-testing a purchase, and current owners tracking equity risk in Flagler Beach. It does not predict a crash. It identifies the variables that matter and shows where a buyer or investor can look for early signs of a softer market.
Flagler Beach Market Snapshot - 2026
A useful risk baseline comes from the relationship among inventory, days on market, price reductions, and pending-sales activity. When comparable listings accumulate, marketing periods lengthen, and sellers cut prices more often, negotiating leverage can shift before closed-sale prices clearly change.
For Flagler Beach, review those measures monthly within the same property type, condition range, and price band. Coastal homes can have materially different insurance, maintenance, and flood-related costs, so broad market averages may not reflect the competition for a specific property.
Supply-Side Risk: What New Inventory Could Do to Flagler Beach Real Estate Risks
Supply-side risk is moderate because Flagler Beach has limited ability to add large volumes of interchangeable coastal housing, but the effective supply facing a buyer can still increase quickly. New listings, renovated resales, homes returning after an unsuccessful listing period, and newly completed properties can all compete for the same relocation or investment buyer.
The practical question is not simply whether a large master-planned community is being built within Flagler Beach. It is whether buyers can choose among more comparable homes with newer roofs, updated systems, wind-mitigation documentation, lower expected maintenance, or more predictable insurance options. When several properties satisfy the same need, sellers may need to offer concessions or accept longer marketing periods.
The City of Flagler Beach processes building and planning applications through its Planning, Building & Engineering Department. Buyers should review public planning agendas and permit activity for projects that could introduce directly comparable housing or alter access, views, drainage, and neighborhood character.
This is not necessarily a high appreciation risk because a beach location is difficult to replicate. It becomes more meaningful for older homes with deferred maintenance, unusual layouts, or high recurring costs. Track new comparable listings, relists, and price changes rather than assuming limited land automatically guarantees pricing power.
Demand-Side Risk: Employment, Population, and Migration Trends
Demand-side risk is moderate because Flagler Beach depends on lifestyle-driven demand as well as the broader regional economy. A buyer pool that includes retirees, relocating households, second-home purchasers, and investors can be resilient, but it may also become cautious when financing costs, insurance quotes, or market uncertainty rise.
Employment among local residents is spread across sectors including education, health care, retail, accommodations, construction, administration, finance, and real estate. That mix reduces reliance on one employer, although consumer spending, tourism-linked activity, and regional job conditions can still influence confidence and housing demand.
The Flagler Beach postal-city area has a population record of 7,532, with a median age of 58 (Flagler Beach, FL). Those characteristics point to a market where retirement timing, equity-market conditions, health-care access, and the cost of maintaining a coastal home can influence purchase decisions.
Watch pending sales, showing activity, withdrawn listings, and repeated price reductions. A decline in buyer engagement matters most when it occurs alongside an increase in similarly priced homes for sale.
Affordability Ceiling: When Flagler Beach Real Estate Risks Meet Buyer Purchasing Power
Affordability is a central Flagler Beach real estate risk because total ownership costs can rise faster than the budgets of financed buyers. The postal-city area’s median home value is $279,849 and median household income is $55,230, creating a broad value-to-income screen of roughly 5.1 to 1. This is not a lending calculation, but it shows why price alone does not define affordability (Flagler Beach, FL).
The same source reports an overall cost-of-living index of 136.6, compared with a national benchmark of 100. Housing, transportation, and utilities are also above that benchmark. For a relocation buyer, those recurring expenses can reduce the amount available for principal and interest, particularly when a home also requires flood coverage, wind coverage, association dues, or near-term repairs.
Prices commonly lose momentum when sellers continue using stronger prior sales as reference points while buyers qualify for less. Mortgage-rate changes matter because they immediately affect the financed portion of the buyer pool. Test the property using realistic insurance, tax, maintenance, and financing assumptions instead of relying on a future refinance to make the payment work.
Risk Factor Scorecard: Flagler Beach vs. Comparable Markets
A reliable numerical comparison requires the same reporting period, property type, and geographic boundary across every market. For a practical Flagler Beach comparison, assess each nearby alternative using the following risk dimensions:
- Months of supply for comparable homes
- Value-to-income relationship and total monthly payment
- Price reductions and closed-sale direction
- Permit and construction activity relative to housing stock
- Rental operating costs, vacancy exposure, and local rules
A coastal home should be compared with similar coastal homes, not with a broad regional median. The strongest risk signal is a combination of rising choices, weaker pending sales, and higher carrying costs.
Interest Rate Sensitivity: How Rate Moves Hit Flagler Beach Specifically
Flagler Beach is moderately sensitive to interest-rate changes because its buyer pool can include financed relocation households, move-up buyers using equity, cash purchasers, and investors. Cash and equity buyers may be less directly affected by rate increases, but financed buyers can reset their budgets quickly when borrowing costs rise.
During the 2022–2023 rate cycle, higher borrowing costs changed buyer behavior faster than many sellers adjusted asking prices. In this market, that effect is amplified when the mortgage payment is paired with insurance, taxes, maintenance, and association expenses. A home that works at one payment level can appeal to a much smaller resale pool when rates move higher.
The downside risk is lower for properties that remain affordable under several payment scenarios. Buyers should evaluate a home at today’s rate, a moderately higher rate, and with a conservative insurance estimate before treating projected appreciation as part of the investment case.
Investor Concentration Risk
Risk label: Monitor rental economics before assuming investor demand will support resale value. The Flagler Beach postal-city area has a renter-occupied share of 18.93% and a vacancy measure of 28.93%. Those figures do not establish investor ownership, but they support careful property-level analysis of occupancy, operating costs, and realistic rental income. If returns compress, owners with thin margins may become more willing to sell at the same time.
Understanding investment risks is only one part of evaluating a Flagler Beach property. Rental income potential, operating expenses, insurance costs, and long-term resale demand should also factor into your decision. For a broader perspective, explore our guide to evaluating real estate investment opportunities in Flagler Beach to better understand what to consider before purchasing an investment property along Florida's coast.
Environmental and Insurance Risk: The Hidden Appreciation Drag
Environmental and insurance exposure are significant Flagler Beach real estate risks because coastal conditions can affect both the monthly payment and a home’s future buyer pool. Flood exposure, elevation, roof age, wind-mitigation features, drainage, deductibles, and prior claims history can create major cost differences between homes that appear similar at first glance.
Buyers should confirm flood-zone status and map information by address through the FEMA Flood Map Service Center. FEMA mapping is a starting point, not a substitute for reviewing the property’s elevation documentation, insurance history, inspection findings, and lender requirements.
Insurance shopping should begin early. The Florida Office of Insurance Regulation provides a homeowners rate-comparison tool, but individual premiums depend on the property, coverage choices, deductible, mitigation features, claims record, and carrier underwriting. A higher premium or a restrictive coverage option can reduce what a future financed buyer can pay.
Homes with clear mitigation documentation, a well-maintained roof, and predictable coverage costs may have a wider resale audience than comparable properties with uncertain insurance outcomes. Treat insurance quotes as part of the property analysis, not a final administrative step.
Regulatory and Tax Risk: Policy Changes That Affect Flagler Beach Values
Regulatory and tax risk primarily affects Flagler Beach values through ownership costs and permitted rental use. The City of Flagler Beach requires short-term-rental permitting, so investors should review the applicable permit requirements, fees, occupancy rules, and local operating standards before projecting rental income.
Property taxes also deserve address-level review. The Flagler County Property Appraiser explains that a change in ownership can bring assessed value closer to market value, which can produce a tax bill that differs from the seller’s current bill. Homestead protections and exemptions may not transfer automatically to a buyer.
The relevant public bodies are the Flagler Beach City Commission, the city’s planning staff, and the Flagler County Property Appraiser. Buyers should review city agendas, rental requirements, and the parcel’s tax record before removing contingencies. A property with narrow affordability margins can become less competitive if taxes, insurance, or rental compliance costs increase.
Pro-Tip: Track active comparable listings and price reductions in your target price range every month. Those measures often reveal weakening seller leverage before closed-sale pricing catches up.
Make a Confident Move in Flagler Beach
Flagler Beach real estate risks are easier to assess when buyers look beyond views and asking prices. Review comparable inventory, total ownership costs, insurance terms, tax assumptions, and resale competition before deciding what a property is worth.
For a straight-talking review of a Flagler Beach property or neighborhood, call 1 3864459911 or use the contact page to discuss the relevant market data.
Frequently Asked Questions
Is Flagler Beach real estate at risk of a price drop?
A price decline is possible when buyer demand weakens while comparable inventory and ownership costs rise. The most useful evidence is the monthly pattern in active listings, price reductions, pending sales, and days on market for similar homes.
What is the biggest factor that could slow appreciation in Flagler Beach?
The largest constraint is usually the complete cost of ownership, especially financing, insurance, taxes, maintenance, and association expenses. The Flagler Beach postal-city area’s value-to-income relationship reinforces the need to assess buyer purchasing power rather than relying on list-price trends alone.
How does Flagler Beach compare to nearby markets for investment risk?
Flagler Beach has coastal demand, but each investment should be compared with nearby alternatives using the same property type, price band, supply level, and operating-cost assumptions. City planning records and comparable-listing activity provide a more useful comparison than broad regional averages.
How do rising insurance or property-tax costs affect home values in Flagler Beach?
Higher recurring costs reduce the amount a financed buyer can allocate to purchase price. FEMA map information, carrier quotes, and Flagler County property-tax records help buyers estimate those costs before they become a resale issue.
What signs should buyers watch to know if the Flagler Beach market is weakening?
Rising inventory, longer marketing periods, repeated price cuts, fewer pending sales, and relisted properties are early signs of softer demand. Buyers should also monitor changes in insurance quotes because ownership-cost pressure can shrink the qualified buyer pool.
Categories
Recent Posts